Tesla’s third-quarter results put a clear price on its push beyond electric cars. Revenue was almost unchanged from a year earlier at $28.05 billion, while operating profit fell 56% to $718 million as spending on AI, robotics and manufacturing rose. The company still generated positive free cash flow, but its latest figures make the tension between today’s car business and tomorrow’s ambitions harder to ignore.
In its official shareholder update, Tesla reported GAAP net income attributable to shareholders of $787 million, down 43% from $1.37 billion a year earlier. GAAP diluted earnings per share fell to $0.22 from $0.39. On an adjusted basis, earnings were $0.48 per share, compared with $0.50 a year ago. CNBC reported that the adjusted figure topped the $0.43 analysts expected, while revenue narrowly exceeded estimates of $27.9 billion. The distinction matters: the earnings beat was on an adjusted measure, not GAAP profit.
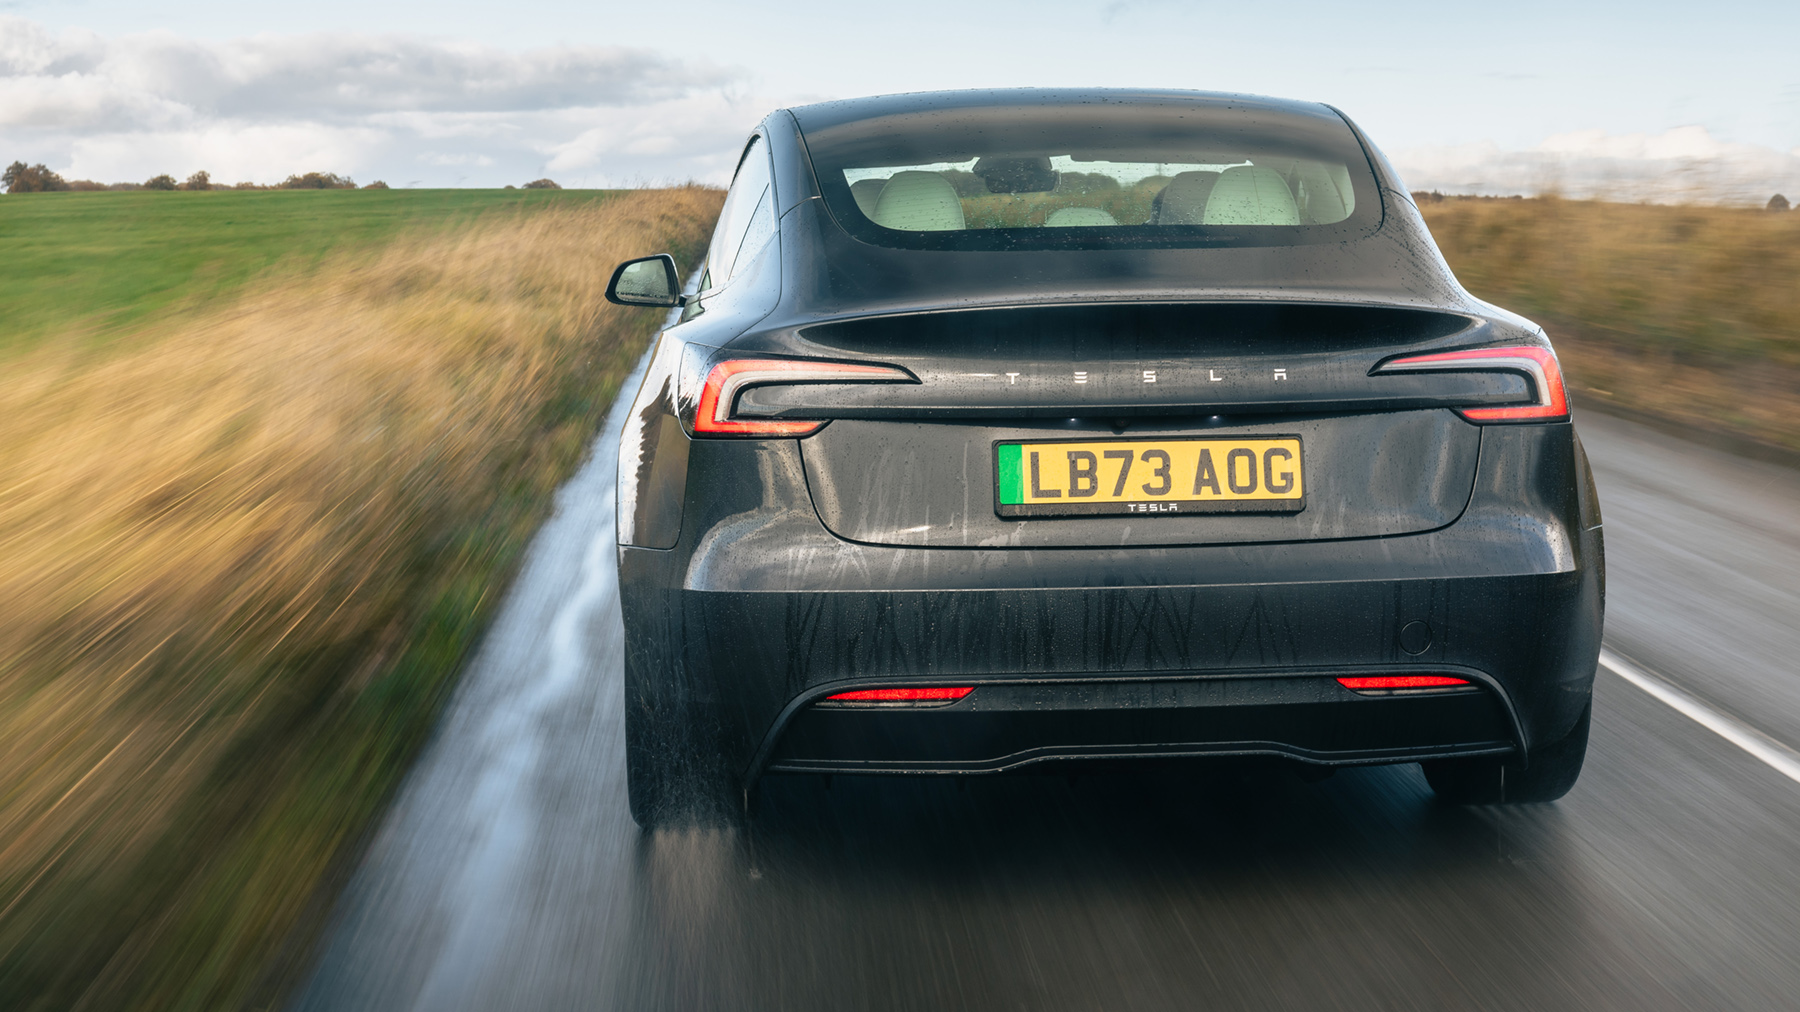
Automotive revenue was $20.56 billion, down 3% year on year, even though Tesla delivered 486,532 vehicles during the quarter. Deliveries were 2% lower than a year ago, and the company produced 464,391 vehicles. Sales of Model 3 and Model Y remained the bulk of the total, with 478,237 deliveries. Other models accounted for 8,295 deliveries, almost half the year-earlier figure.
The headline revenue figure also conceals a changing mix. Energy generation and storage revenue fell 16% to $2.88 billion despite a record 13.7 gigawatt-hours of storage deployments. Services and other revenue, by contrast, grew 33% to $4.61 billion. Tesla did improve its overall gross margin to 19.6% from 18.0%, but operating expenses jumped 39% to $4.78 billion. That left an operating margin of 2.6%, less than half the 5.8% recorded a year earlier.
Tesla produced $6.26 billion in operating cash flow and spent $4.73 billion on capital expenditure, leaving free cash flow of $1.53 billion. Free cash flow was nevertheless 62% below last year’s quarter as capital expenditure more than doubled. Cash, equivalents and short-term investments ended September at $45.45 billion. These figures show that Tesla can finance a substantial portion of its investment internally, but also that the spending is already consuming a greater share of the cash generated by its operations.
The company says more than 75% of new vehicle deliveries in North America included an FSD subscription, and active FSD subscriptions reached 1.74 million, up 67% year on year. FSD remains a supervised driver-assistance product, not a fully autonomous system. Tesla also says it added Cybercabs to its Austin robotaxi fleet and began production of Tesla Semi and Optimus units. Those are notable operational milestones, but the quarterly report does not establish that these ventures are yet making a material contribution to profit.
The contrast with TechBooky’s coverage of Tesla’s second-quarter results is instructive. Revenue remains substantial and the balance sheet remains strong, yet operating profit has weakened as the company spends to build a different kind of business. For investors, the next test is whether software, robotaxis, robotics and energy can add enough durable earnings to justify that investment without relying on expectations alone.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Femi Balo is the founder and publisher of TechBooky. He covers artificial intelligence, African technology, digital infrastructure, enterprise technology and the global digital economy.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.