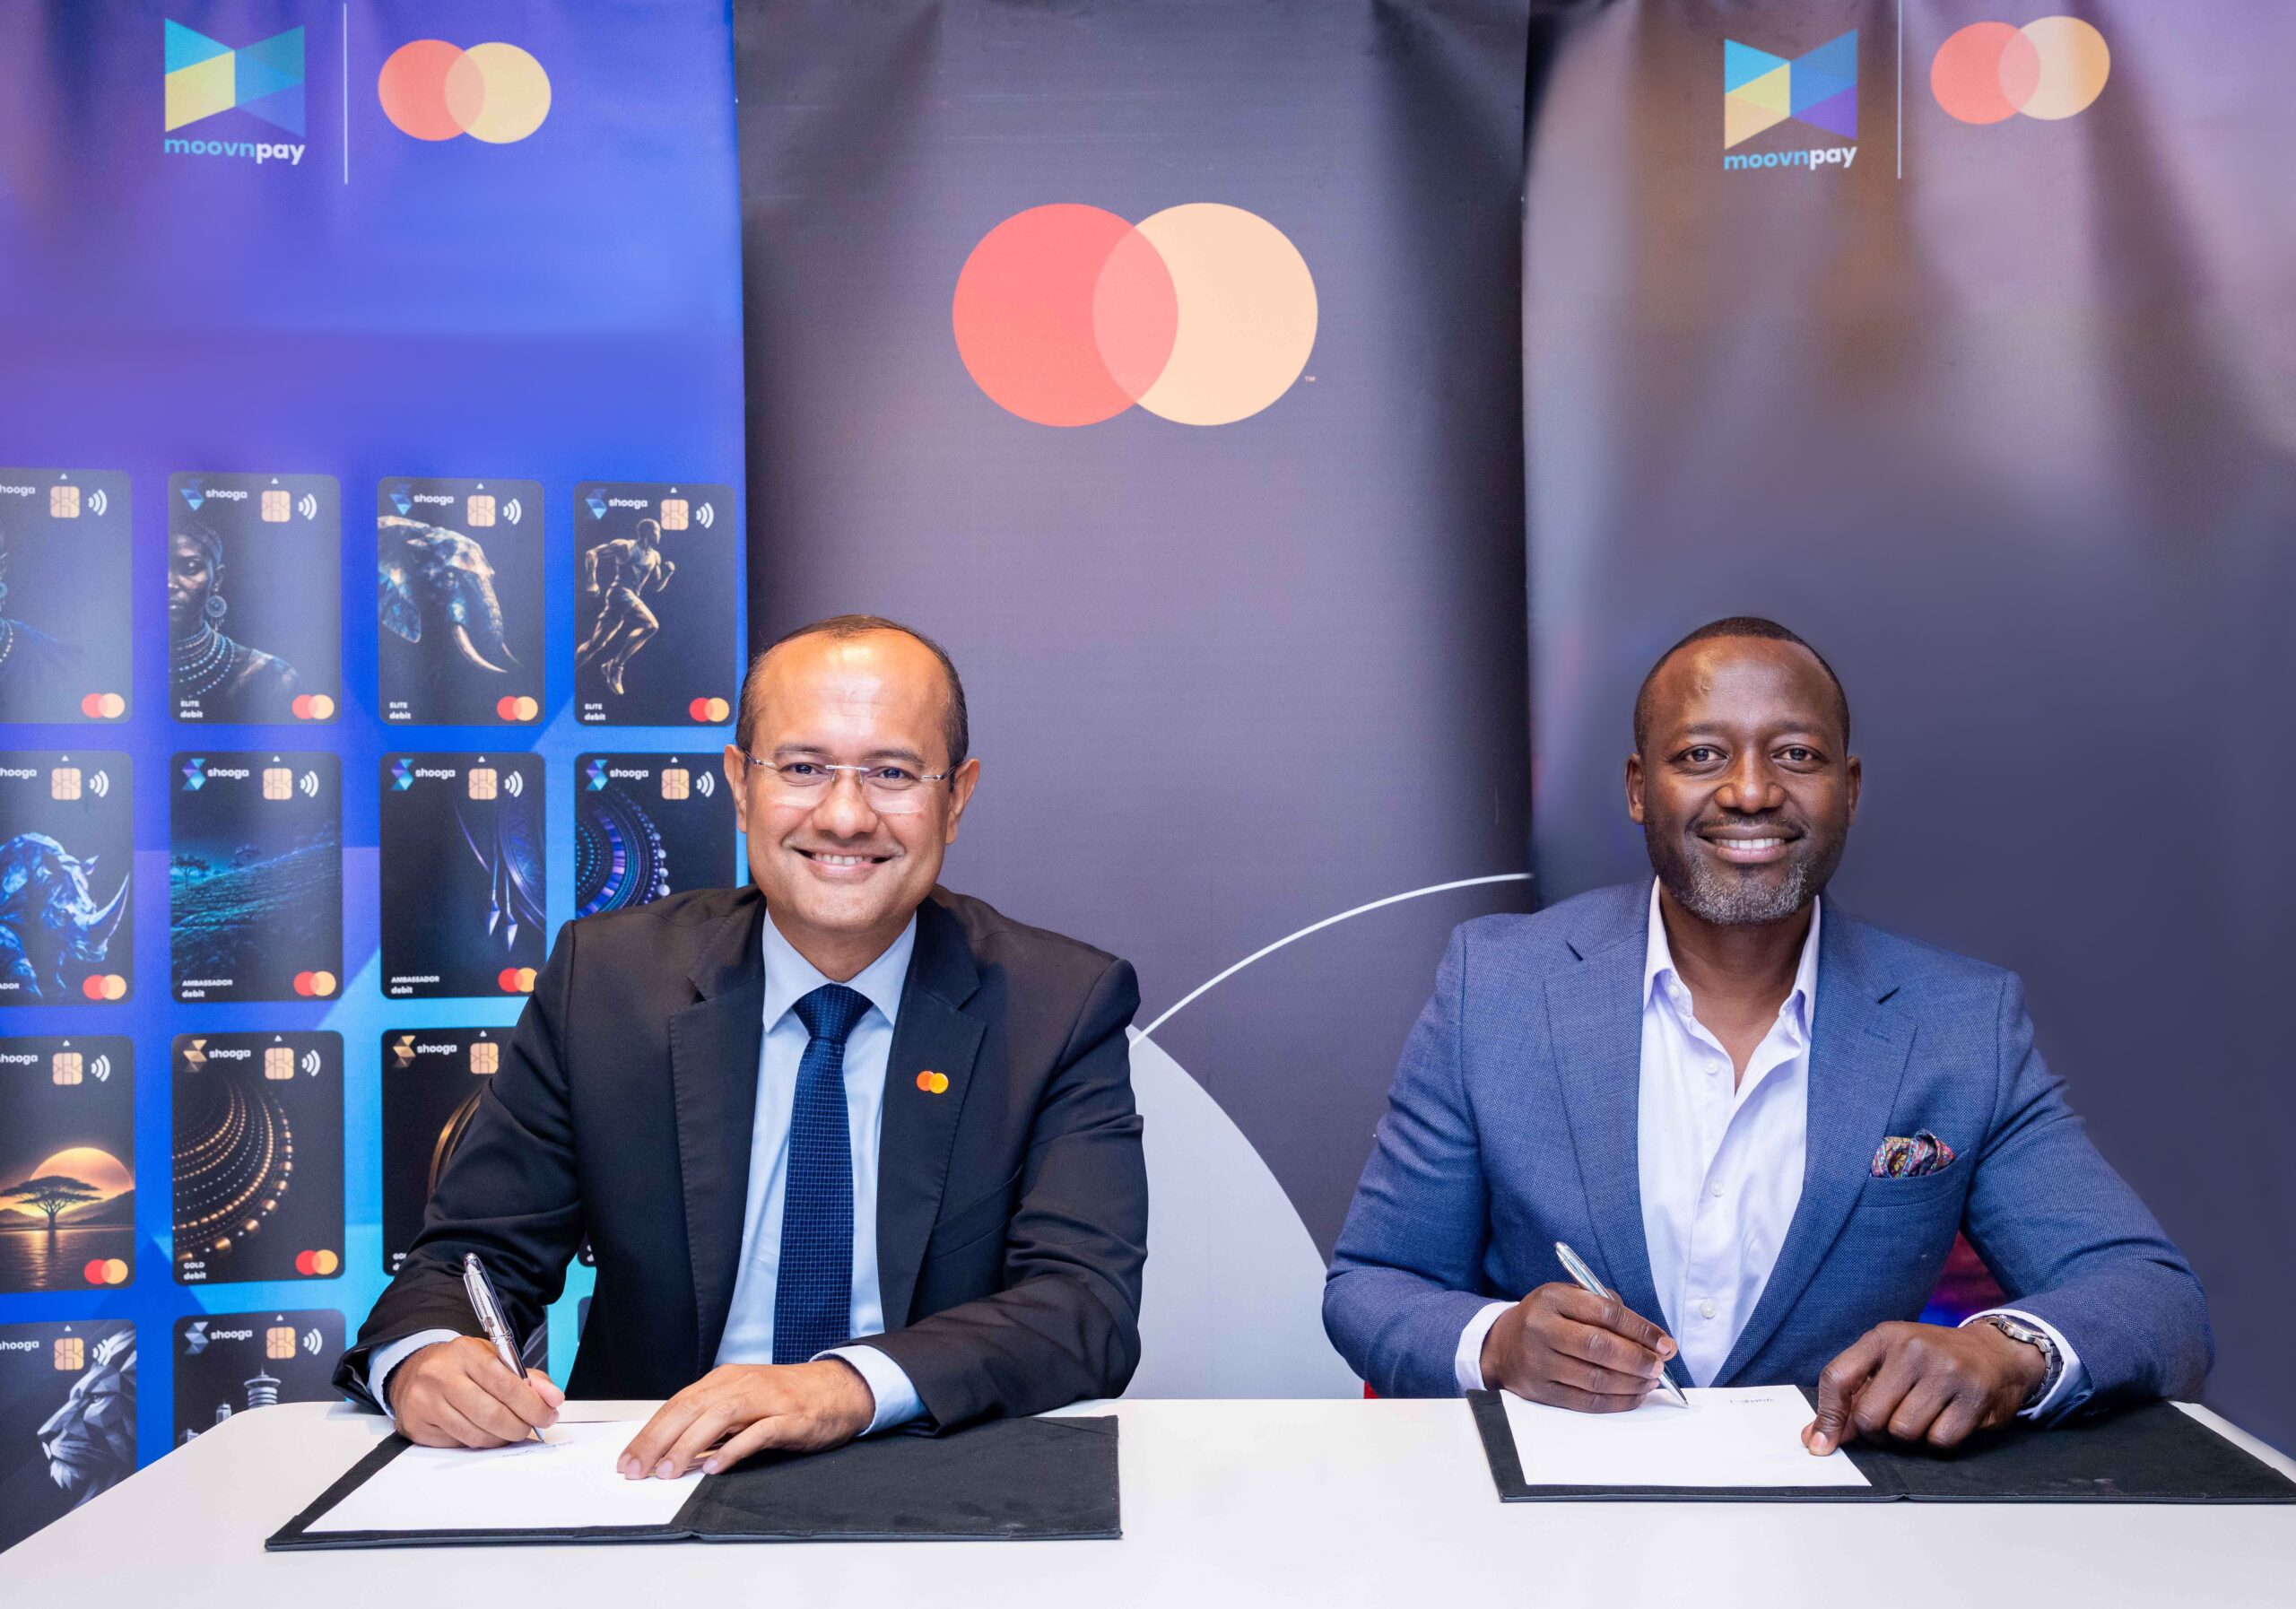
Shehryar Ali, senior vice president and country manager for East Africa and Indian Ocean Islands at Mastercard, and Godwin Gabriel, founder and group chief executive of Moovn Technologies, sign a five-year strategic agreement to expand secure digital payment capabilities across East Africa.
Mastercard and Moovn Technologies have signed a five-year agreement to expand digital payments across East Africa, putting cards, merchant acceptance and cross-border services inside a platform that began with mobility. The companies announced the deal in Nairobi on October 19. Their immediate focus includes Kenya and Tanzania, although they also describe ambitions in other African markets.
The partnership is more than a new way to pay for a ride. Moovn plans to connect its MoovnPay wallet to virtual and physical prepaid Mastercard cards, online and in-app checkout, peer-to-peer payments and eligible international transfers. It also expects those tools to work across its logistics, commerce and merchant services. If the rollout succeeds, drivers and small businesses could receive money, spend it and accept payments without leaving the wider Moovn ecosystem.
Mastercard says MoovnPay will use its payment gateway for online and in-app acceptance, while tokenization will help protect card credentials. The planned Shooga prepaid card portfolio is meant to give wallet users another way to pay. Mastercard’s Pay Local service is expected to let participating merchants in Kenya and Tanzania take payments directly from MoovnPay users as it expands. Eligible cross-border transfers would be supported through Mastercard Move.
Those are planned capabilities, not a claim that every product is available in every market today. The companies say the next phase will focus on Shooga cards, Pay Local’s expansion and broader gateway, tokenization and wallet integration. They have not set out a country-by-country launch calendar, disclosed prices for users or said how many merchants are already live on the new services. Those details will determine how useful the agreement becomes beyond its announcement.
Moovn is not starting from zero. Its payments arm was selected for Mastercard’s Start Path Emerging Fintech program in 2025, and the company has already launched Mastercard Payment Gateway Services in Kenya. This agreement takes an existing relationship toward a larger commercial rollout. It gives Moovn access to established card and payment infrastructure while offering Mastercard a route into transactions generated by transport, delivery and everyday commerce.
Mobility platforms see money move in several directions at once. A passenger pays a fare; a driver receives earnings; a merchant buys goods or pays for delivery. If each step depends on a separate app or cash settlement, the experience can become slower and harder to reconcile. A wallet linked to cards and merchant tools could reduce some of that friction, but only if the service is reliable, widely accepted and priced competitively.
Kenya is already a demanding test market for any new payments proposition. Mobile money is deeply embedded in daily trade, and TechBooky recently reported on M-PESA’s move toward tap-to-pay at shop counters. Moovn and Mastercard therefore need to offer a practical advantage to drivers, merchants and travellers, not merely another place to hold a balance. Cross-border utility and integration with real work flows may be their strongest differentiators.
The wider African payments market is also becoming more connected. National instant-payment systems, wallets and card networks are converging, while regulators and providers still have to manage fraud, settlement and interoperability. Nigeria’s work on a national payment stack is one example of the infrastructure shift. The Mastercard-Moovn deal sits on the commercial side of that same question: how to make money move easily between people, platforms and borders.
For now, the clearest news is the five-year commitment and the product roadmap. Whether it changes payment habits will be measured in active users, merchant adoption and dependable transfers, figures the partners have not yet provided. That makes this an important expansion to watch, but not a finished transformation of East African payments.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Balo is the founder of TechBooky and a highly skilled wireless communications professional with a strong background in cloud computing, offering extensive experience in designing, implementing, and managing wireless communication systems.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.