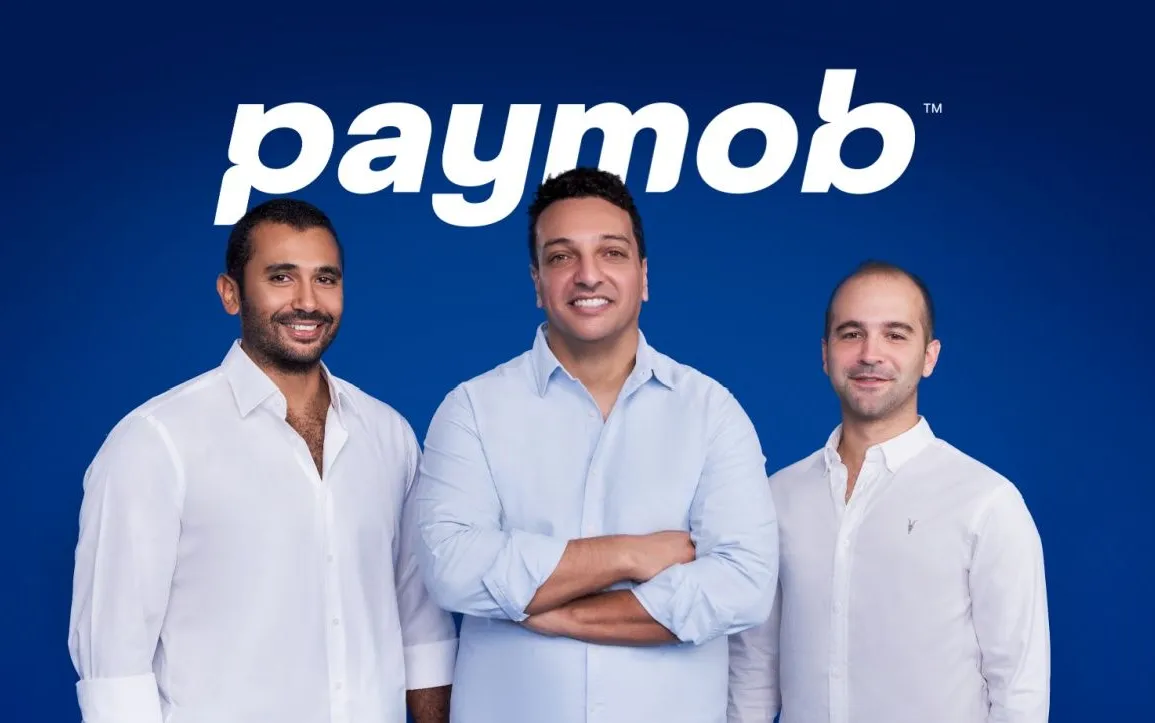
Egyptian payments company Paymob has raised $35 million in a pre-Series C round to expand across the Middle East and North Africa, deepen its services for small businesses and prepare its payment infrastructure for agentic commerce. Mubadala and the European Bank for Reconstruction and Development co-led the investment.
British International Investment, Global Ventures and DPI Venture Capital also participated, according to the official September 21 announcement. The round follows a period in which Paymob says consolidated revenue tripled across its four markets in 18 months, while revenue from the Gulf grew sevenfold.
The numbers show how much the business has changed since it was known mainly as an Egyptian payment gateway. Close to half of Paymob’s revenue now comes from Gulf markets, turning the company into a broader regional platform with operations in Egypt, the United Arab Emirates, Saudi Arabia and Oman.
Paymob wants to solve a problem familiar to merchants across MENA. Payment systems are fragmented between local card networks, bank instalment products, buy-now-pay-later providers and digital wallets. A business entering several countries may need separate contracts, technical integrations and settlement processes for each market.
The company’s answer is one contract, one API and one dashboard covering more than 60 payment methods. Paymob says over 390,000 merchants use its platform to accept online and in-store payments, manage transactions and access financial services. That scale gives the company a stronger base for adding products around lending, business management and automated commerce.
Agentic commerce is the forward-looking part of the announcement. It describes shopping in which AI agents can search, compare and potentially complete purchases on behalf of users. For payment providers, that creates new questions around identity, consent, fraud and how a merchant knows that an autonomous agent is authorised to spend a customer’s money.
Paymob says some of the new capital will accelerate a product roadmap aimed at becoming the payments platform for that market. The idea is early, but it is strategically sensible. Payment companies do not want to discover that AI agents have changed the checkout process while their infrastructure still assumes every transaction begins with a person clicking a button.
The funding also gives Paymob more room to expand its core merchant business. Since receiving a Retail Payment Services Licence from the Central Bank of the UAE in January 2025, it has onboarded roughly 20,000 merchants across its three Gulf markets. Saudi Arabia and Oman provide further growth opportunities as governments encourage cashless payments and small businesses adopt more digital tools.
Paymob’s investor list now includes PayPal Ventures, Kora Capital, FMO, A15 and several development-finance institutions. TechBooky’s earlier look at Paymob’s $50 million Series B showed a company trying to move beyond online checkout into omnichannel payments. Four years later, the new round is about turning that foundation into a regional network.
There are still execution risks. Each country has different licensing rules, banking relationships and consumer habits. Competition is also intense, with banks, global processors and local fintechs pursuing the same merchants. Rapid Gulf growth will need to become durable revenue rather than expensive customer acquisition.
Even so, the round is a positive signal for African and Middle Eastern fintech. Investors are backing a company that has moved from one home market into regulated regional operations and can point to real merchant adoption. Paymob’s next test is whether it can use that scale to become the payment layer for both today’s businesses and tomorrow’s AI-assisted shopping.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Balo is the founder of TechBooky and a highly skilled wireless communications professional with a strong background in cloud computing, offering extensive experience in designing, implementing, and managing wireless communication systems.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.