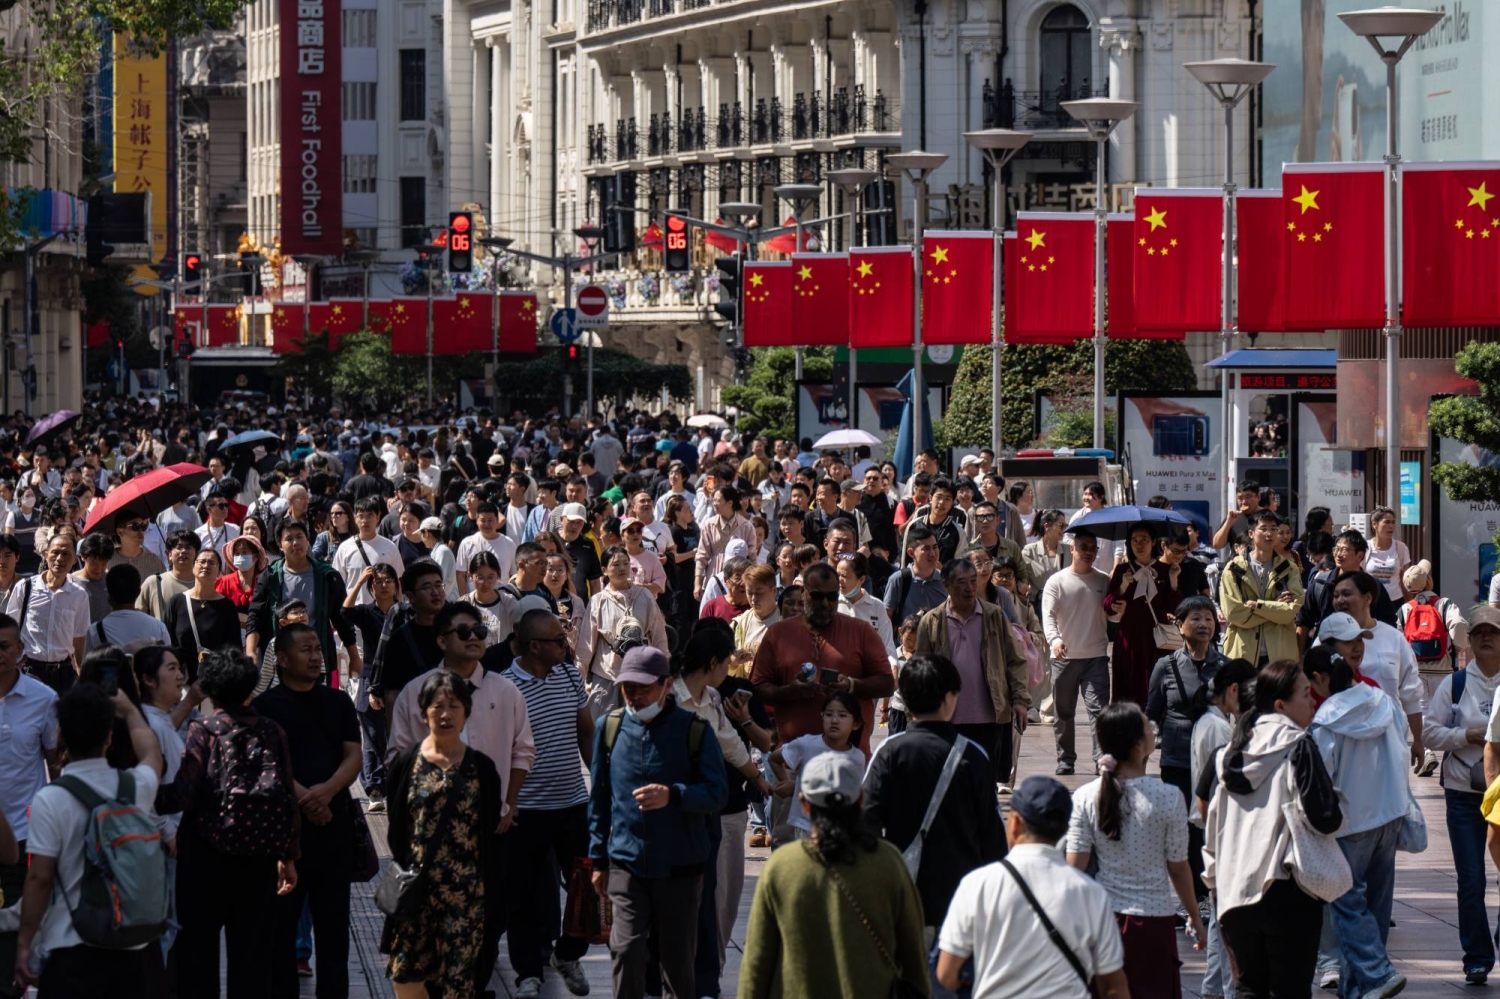
Nanjing Road during the Golden Week holiday in Shanghai, China, on Monday, Oct. 5, 2026. August retail sales crept up just 0.4%, and there are few signs that investor pessimism toward the sector will ease after Golden Week, a crucial period for travel and spending. Photographer: Qilai Shen/Bloomberg
China’s economy grew 4.5% from a year earlier in the third quarter of 2026, accelerating from 4.3% in the second quarter, according to official figures released on Monday, October 19. The improvement is real, but the data tell a more complicated story than a simple rebound. Technology manufacturing and exports are doing much of the work, while consumer spending and property investment remain weak.
For technology companies and investors, that split matters. China is still expanding its capacity to make and sell advanced goods, even as the domestic households and businesses that might buy them are more cautious. The result is an economy that can look surprisingly strong from a factory floor and much less comfortable from a shopping street.
The National Bureau of Statistics said value added at high-tech manufacturers rose 14.3% in the first nine months of the year. Equipment manufacturing grew 10.2%, while the information transmission, software and IT services sector expanded 10.4%. These figures cover broad industries rather than artificial intelligence alone. They support the case that China’s industrial and digital sectors are growing, but they do not prove that AI itself caused the GDP acceleration.
Exports offer a second source of momentum. In yuan terms, China’s exports rose 16.4% over the first three quarters, with mechanical and electrical products up 23.7%. Those products accounted for 64.3% of exports. Overseas demand can help factories keep operating and investing even when Chinese consumers are less willing to spend.
The headline GDP figure also needs context. Output rose 1.2% from the previous quarter, according to the statistics bureau. A Reuters report noted that the annual figure was above the 4.4% median forecast in its poll of economists. That is a modest upside surprise, not evidence that every part of the economy is recovering at the same pace.
Retail sales of consumer goods increased only 1.1% in the first nine months, and September’s annual increase was also 1.1%. Fixed-asset investment fell 7.2% over the period, with property development investment down 20.6%. Those numbers explain why a technology-led growth story can coexist with a sense of weakness at home. Factories can receive foreign orders while developers, local suppliers and households face a very different reality.
The distinction is relevant to the global AI race. Stronger electronics and equipment output can support Chinese chipmakers, cloud suppliers and model developers, but there is a difference between producing technology and turning it into broad domestic productivity or consumer demand. TechBooky’s recent coverage of Huawei’s challenge to Nvidia in China shows how quickly the supply side can change. GDP data alone cannot tell us whether those gains are spreading across the wider economy.
Export reliance also carries a risk. If overseas demand weakens or trade restrictions tighten, the strongest part of the current picture could come under pressure. Conversely, firmer consumer spending would make the expansion less dependent on factories selling abroad. That is why the next retail, property and investment readings may say more about the durability of China’s recovery than the headline GDP number by itself.
For now, China’s third quarter provides a clear but narrow signal; growth picked up, and high-tech industry remains a standout. The open question is whether that industrial strength can pull the domestic economy along with it.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Balo is the founder of TechBooky and a highly skilled wireless communications professional with a strong background in cloud computing, offering extensive experience in designing, implementing, and managing wireless communication systems.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.