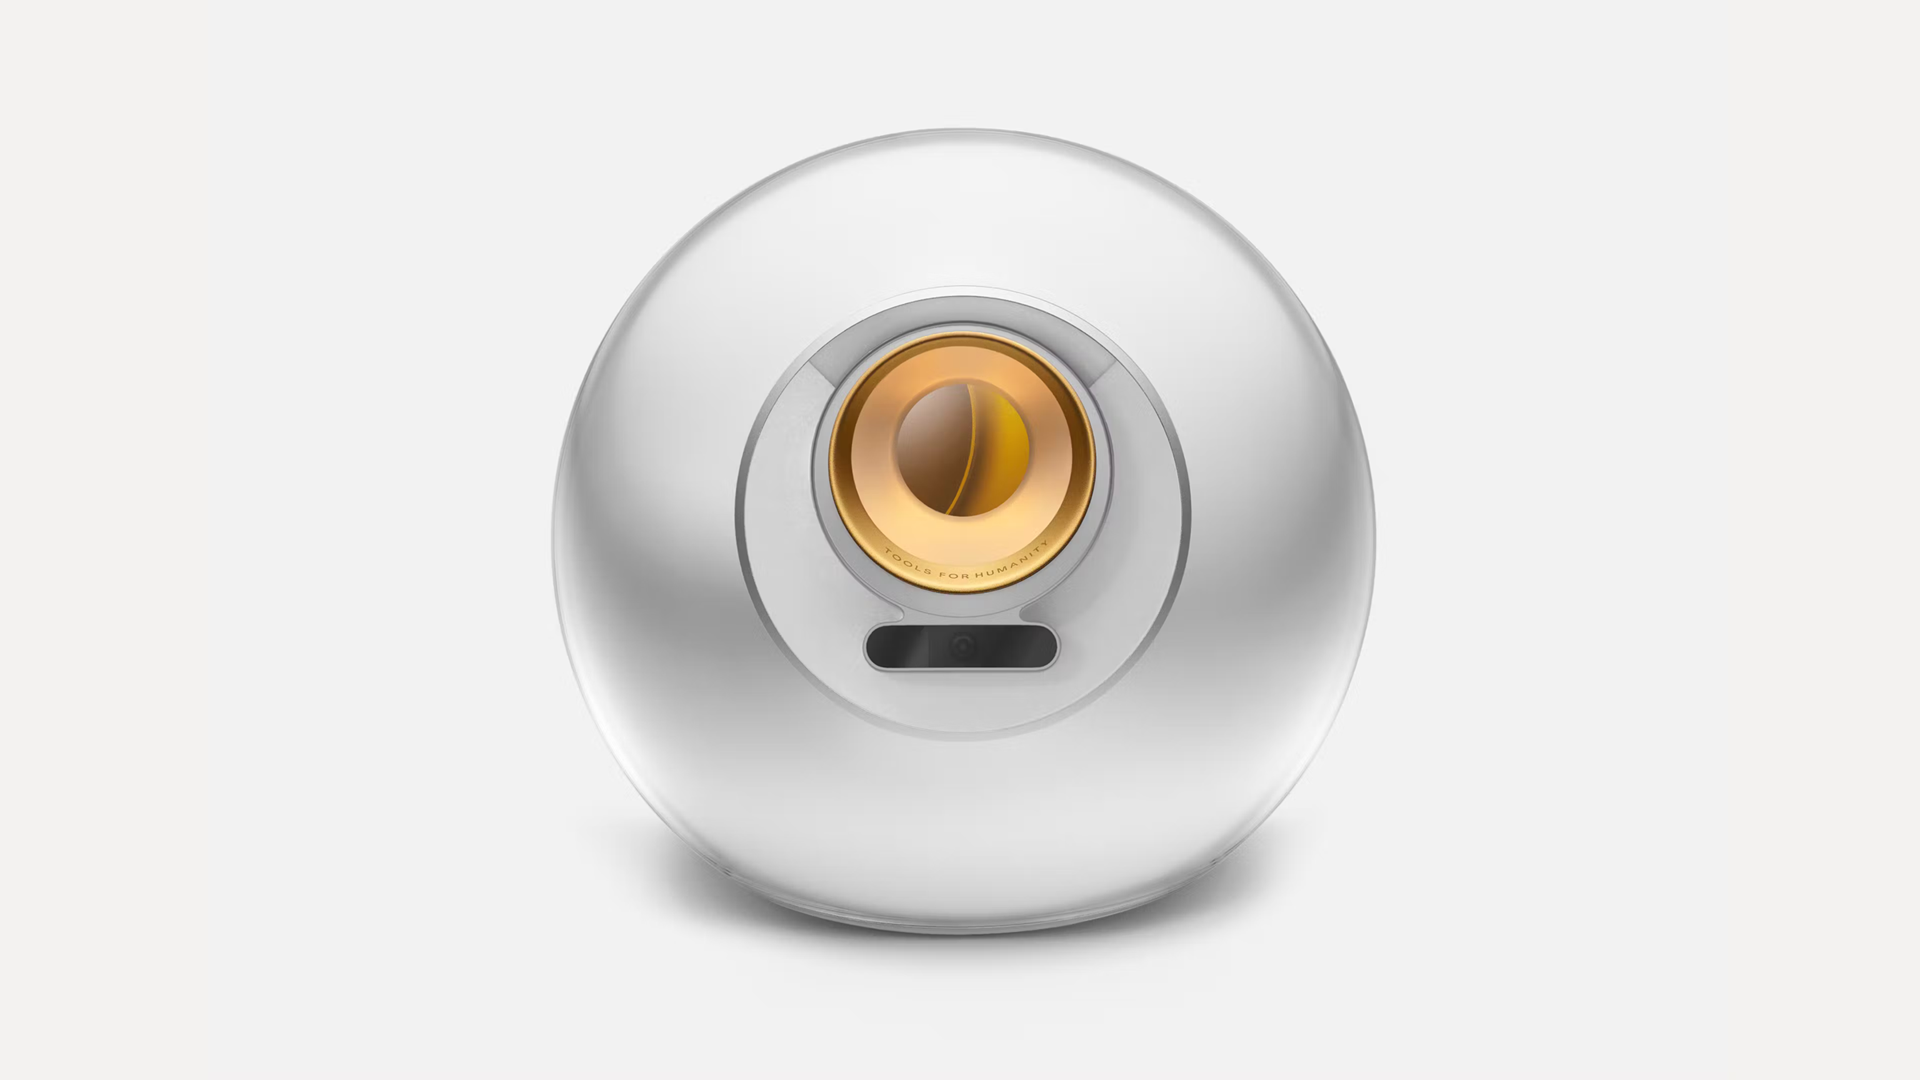
Sam Altman’s World is taking its proof-of-human technology into banking and finance, where an AI-generated face, voice or message can have far more serious consequences than a fake social media account. At Money20/20 in Las Vegas, co-founder Alex Blania introduced a World ID suite intended to help financial firms verify that a person is real and present during sensitive digital interactions. The company’s October 18 announcement names Bain Capital, OpenExchange, Outtake, Pantera Capital and VanEck Funds as initial design partners.
That list matters. World has announced a product for the financial sector, not a rollout across named consumer banks. It has not disclosed pricing, the number of institutions using the suite, or a timetable for bank customers to encounter it. For now, the story is about a new attempt to make digital identity work in an era of convincing impersonation.
The World ID app offers three different proofs. Proof of Human is designed to establish that a person is unique and real after a one-time verification at an Orb. Proof of Presence uses a phone-based liveness check to establish that someone is there at the moment of an interaction. Proof of Attributes is intended to confirm facts drawn from an official credential, such as age or nationality, without revealing the whole document. These are different claims, and a bank would have to decide which one fits a particular risk.
Possible uses include new-account checks, high-value transfer approvals and account recovery. World also wants to address impersonation in meetings. Its World ID for Zoom integration gives a verified participant a visible Human Badge after connecting a World ID account and completing a live check. World says Zoom does not receive personal information through that process. AgentKit, which is still in beta, would let a person delegate certain proofs to an AI agent acting on their behalf.
The need is real. The US Financial Crimes Enforcement Network has warned financial institutions about deepfake media being used in fraud, including attempts to bypass identity checks. A video call or a familiar voice is no longer enough on its own to establish who is making a request. That does not mean a single identity product can eliminate fraud, but it explains why banks are testing stronger forms of verification.
World’s pitch is that cryptographic proofs can answer a narrow question without forcing institutions to collect and retain more personal data. In practice, adoption will depend on how well the system works for people who cannot or do not want to use an Orb, what happens when a check fails, and whether banks can explain the process clearly to customers. Financial institutions also have their own legal and compliance duties; a proof of humanness is not automatically a substitute for every know-your-customer requirement.
Those trade-offs will be especially important as digital identity spreads into services people rely on. TechBooky has examined why trust and access matter in Kenya’s digital ID discussions. The same questions apply here such as who can enrol, what is stored, how errors are corrected and whether people still have another route into essential services.
World says more than 18 million people already hold its Proof of Human credential. The financial launch gives that network a potentially consequential new use, but its impact cannot yet be measured by the breadth of the announcement. The more revealing milestones will be live institutional deployments, independent evidence that fraud falls, and clear answers on privacy and accessibility.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Balo is the founder of TechBooky and a highly skilled wireless communications professional with a strong background in cloud computing, offering extensive experience in designing, implementing, and managing wireless communication systems.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.