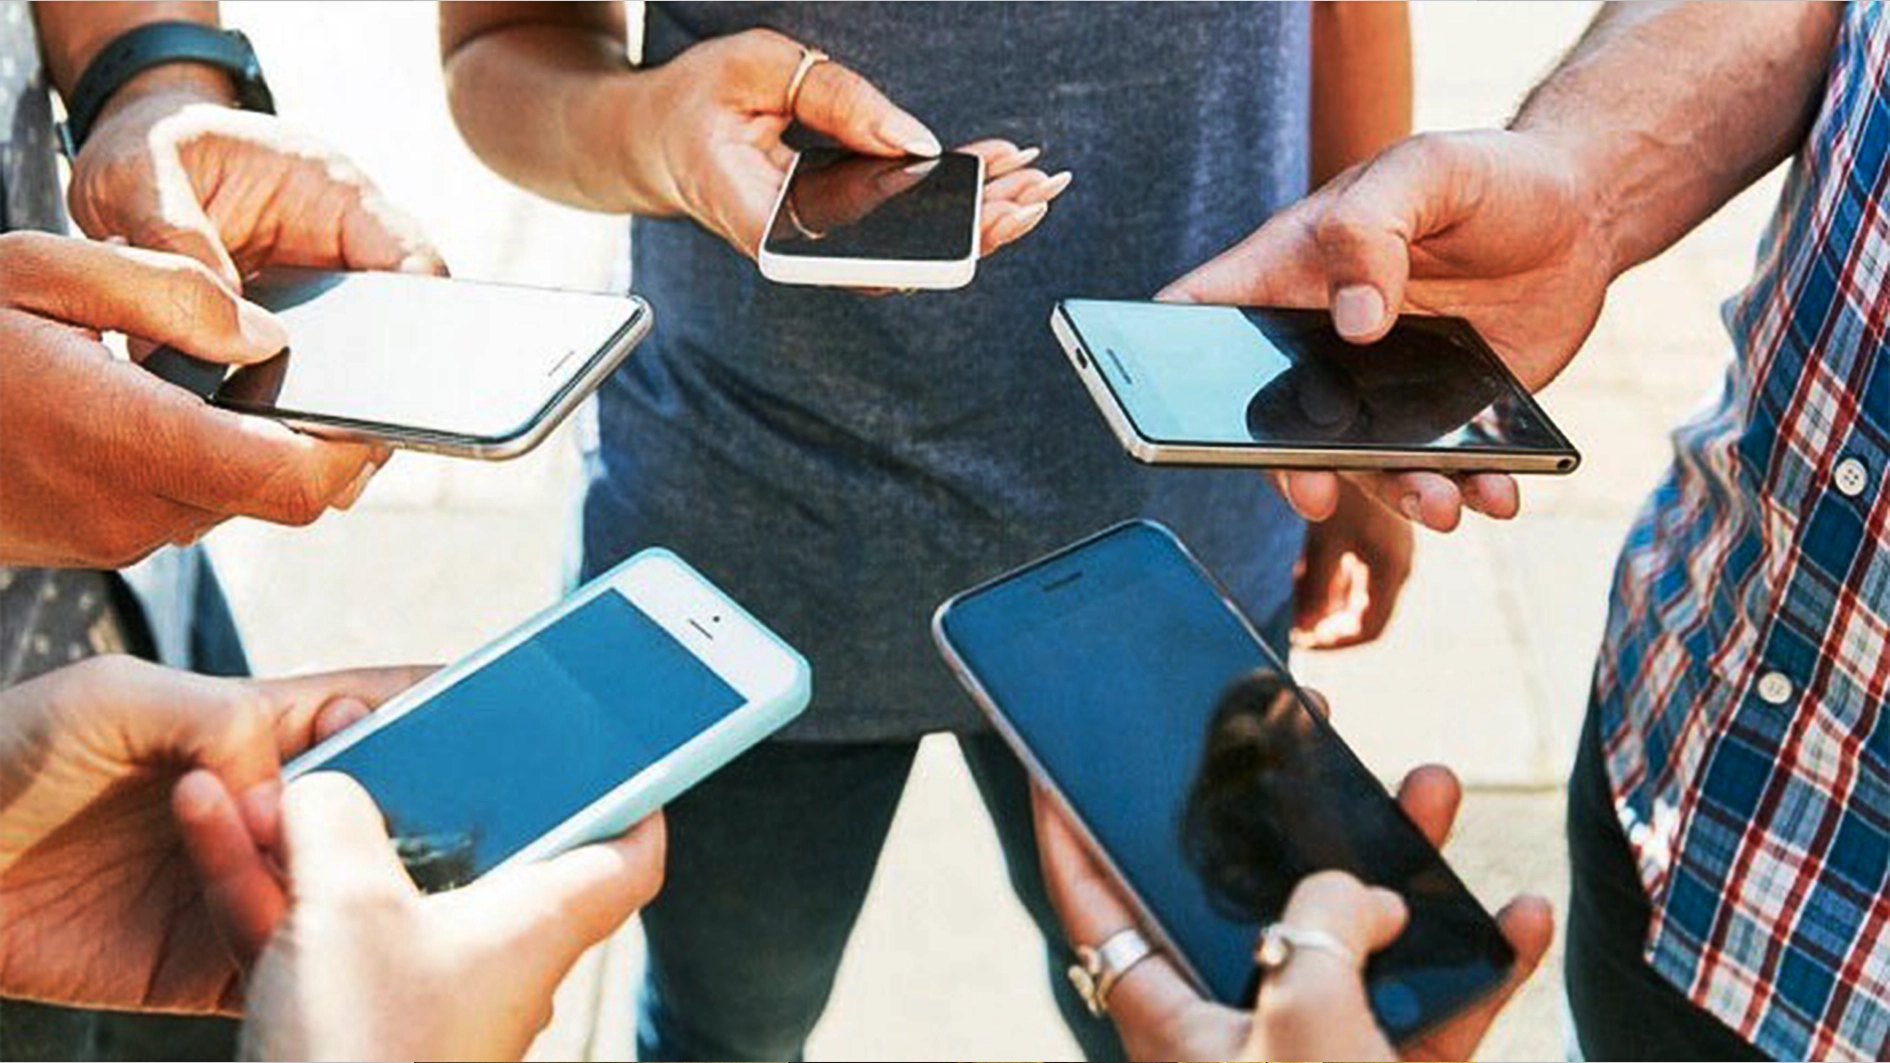
Nigeria’s biggest mobile operators are earning much more from data, but that growth does not settle a question subscribers ask every day. Is the connection they pay for actually improving? A report on 2 November drew attention to complaints about call quality at the same time as telecoms revenue rose. The contrast is worth examining, although reported complaints are not, by themselves, a nationwide measurement of network performance.
The Guardian’s account pointed to the tension between stronger operator income and customer experience. The underlying financial figures come from different businesses and reporting periods, so they must not be treated as a like-for-like comparison. MTN’s Nigerian results cover nine months to September 2026; Airtel Africa’s figures cover six months and 14 markets.
MTN Nigeria’s nine-month release puts service revenue at about N4.6 trillion, up 23.7%, while its data-user base rose 12% to 57.2 million. Its financial statement records data revenue of about N2.68 trillion, up from N1.97 trillion in the comparable period. MTN also reported N864.8 billion in capital expenditure excluding leases, up 14.2%. These figures show the scale of data demand and investment, not a verified change in the quality of an individual subscriber’s connection.
Airtel Africa’s half-year results show group revenue of $3.823 billion, up 28.2% on a reported basis. The company reported 89.9 million data customers across its markets and average smartphone data use of 13.3GB a month, compared with 10.1GB a year earlier. Those are group-wide numbers. They cannot establish the quality of Airtel’s Nigerian network in a particular city or neighbourhood.
More revenue can follow greater usage, price changes, currency effects and an expanding customer base. More data consumption can also place extra strain on busy cells before new capacity catches up. A user may enjoy higher speeds at a quiet hour and still experience congestion at peak time. Voice calls, meanwhile, can suffer from coverage gaps, handover failures or poor indoor reception even when mobile data sales are rising.
The correct test is therefore not simply whether an operator says it is investing. Subscribers need comparable, location-specific evidence on dropped calls, call setup, latency, throughput, outages and congestion over time. Operators and regulators can publish those measures with enough geographic detail to show whether improvements reach areas where complaints are concentrated. Anecdotes can flag a problem, but they should trigger measurement rather than stand in for it.
The distinction matters in a market where mobile connectivity is central to payments, work and access to information. TechBooky’s African technology statistics and trends offers broader context for the continent’s growing digital reliance. For Nigerian subscribers, the real dividend from the data boom should be a service they can depend on, not just a better line in an earnings release.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Femi Balo is the founder and publisher of TechBooky. He covers artificial intelligence, African technology, digital infrastructure, enterprise technology and the global digital economy.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.