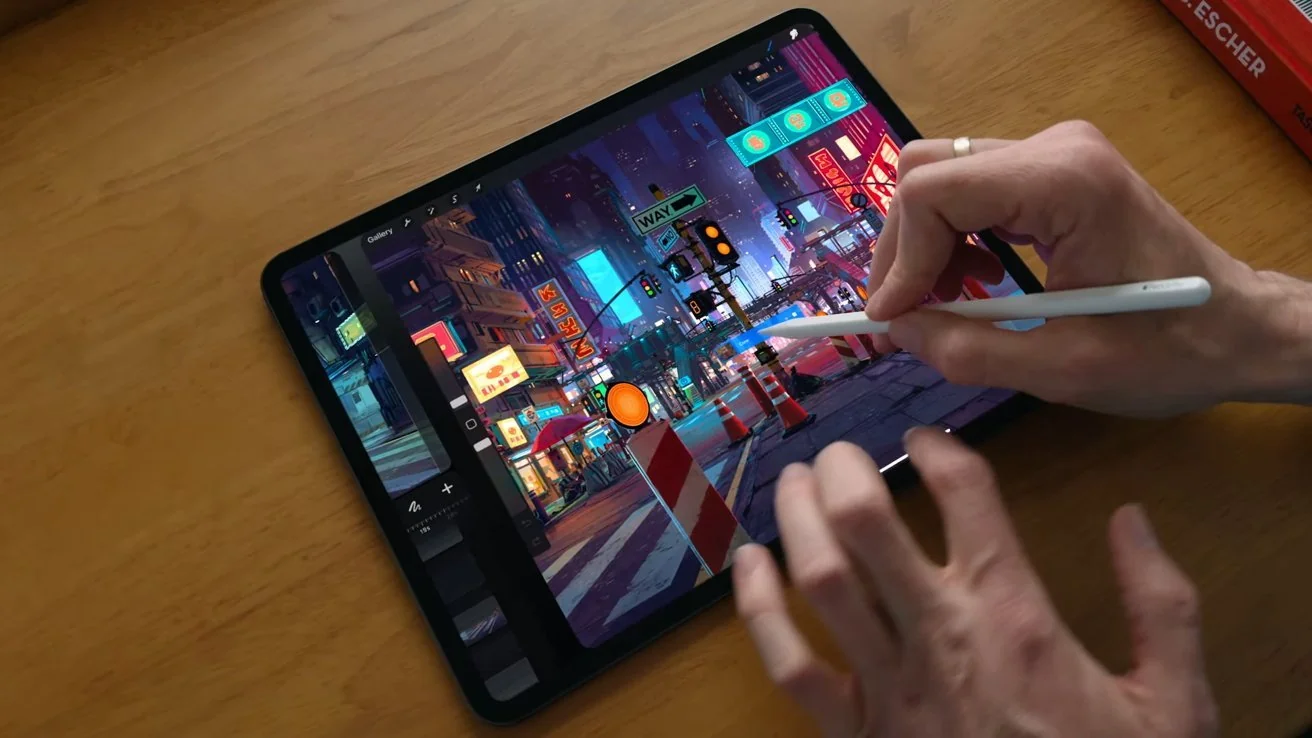
Global tablet shipments fell 23% from a year earlier to about 32 million units in the third quarter of 2026, their lowest level in nearly three years, according to research published by Omdia on 5 November. Apple remained the market leader, but its iPad shipments dropped 27.5% to roughly 11.58 million units. Its share slipped to 36% from 38.2% a year earlier.
The scale of the fall is notable because it comes after a 10% contraction in the previous quarter. In its market report, Omdia says the Middle East, China and Western Europe saw particularly sharp declines. The research firm points to supply constraints, limited improvements between new models and buyers delaying upgrades.
Apple leads a smaller market
Apple still shipped more than twice as many tablets as second-placed Samsung, which sent 5.4 million devices to market, down 22% year on year. Lenovo was the exception among the five largest vendors. Its shipments rose 12% to 4.1 million units, lifting its share to 12.7% from 8.7%. Omdia says stronger demand for conventional slate tablets supported Lenovo, even as detachable models weakened.
Xiaomi ranked fourth with 2.3 million shipments, down 11%, while Huawei shipped 1.8 million, a 43% fall. These figures show that the downturn was broad rather than an isolated iPad problem. Apple lost share because its shipments fell faster than the market overall, but it remains the clear leader in volume.
Shipments are devices supplied to the sales channel, not a count of tablets bought by consumers. A weak quarter may reflect slower demand, existing retailer stock or vendors choosing to hold back inventory. It would therefore be misleading to treat the 23% drop as a precise measure of purchases at the till. Even so, two consecutive quarters of contraction suggest manufacturers are facing a tougher market.
Several companies introduced fresh tablets in the second half of the year, including new Samsung, Apple and Xiaomi models. Omdia argues that launches have not been enough to overcome tighter component supply and the absence of compelling reasons for many owners to replace a working device. If buyers see only modest changes in performance or features, they can put off an upgrade more easily than they might with a phone they rely on every hour.
Omdia’s outlook is cautious. It says meaningful recovery is unlikely before 2028 if supply conditions tighten further next year. That is a forecast, not a recorded outcome, and holiday demand could alter the near-term picture. For now, the figures underline a gap between frequent product announcements and the number of tablets vendors are actually shipping.
TechBooky recently noted that Apple’s iPad revenue also declined in its September quarter, even as iPhone and Services revenue grew. Revenue and shipments measure different things and should not be compared as if they were the same statistic. Together, however, they show that tablets are a weaker part of Apple’s current hardware picture. The next question is whether better specifications, steadier supplies or lower prices can persuade buyers to return.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Femi Balo is the founder and publisher of TechBooky. He covers artificial intelligence, African technology, digital infrastructure, enterprise technology and the global digital economy.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.