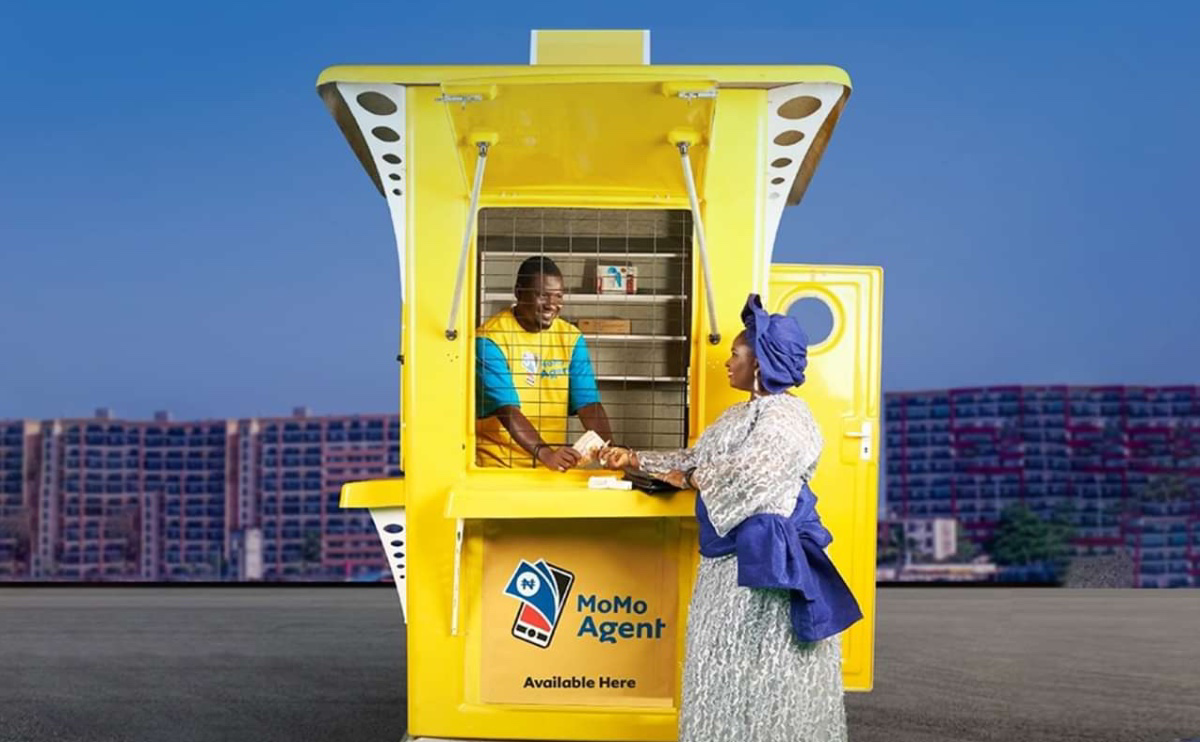
MTN Nigeria’s mobile money operation is growing rapidly, yet its wider fintech business is shrinking. That is the striking split in the company’s results for the nine months to 30 September 2026, released on 30 October. Core mobile money revenue rose 102.2% from a year earlier, while overall fintech revenue fell 25.9%. Both figures can be true because they measure different parts of the business.
The distinction matters for anyone trying to judge whether MTN’s financial services strategy is gaining ground in Nigeria. The MoMo wallet is attracting more money and activity, but a disruption in a separate credit product weighed on the broader division. Treating the 102.2% figure as growth for all of fintech would overstate the recovery. Treating the 25.9% decline as evidence that the wallet is failing would miss the progress in payments.
MTN says higher float income helped lift core mobile money revenue. Customer wallet balances more than quadrupled from the end of December 2025 to N43.8 billion. That gives the company a larger base of funds associated with its wallet business, although float income is not the same as fees earned from customers making more payments.
The drag came from MTN’s airtime and data credit service, which was suspended between April and June. That service sits within the broader fintech category. It has since resumed under a multi-partner model, and its revenue rose 78.5% in the third quarter compared with the second. The rebound was not enough to erase the earlier interruption across the nine-month period.
The contrast also shows why fintech earnings need more than a single headline number. Wallet balances, transaction volumes, active users, lending income and credit-product availability each tell a different part of the story. A business can win more payment activity while losing revenue elsewhere in the same segment.
In August, MoMo Payment Service Bank moved to a new Alipay+ platform. MTN says the change is intended to improve reliability, security and the range of services it can offer. Monthly active users stood at 3.2 million at the end of September, although the company cautions that the figure is measured on the new platform only while older wallets continue to migrate. Third-quarter transaction volumes increased 69.1% from the previous quarter.
Those are encouraging signs, but the migration makes simple comparisons harder. Investors will need to see whether active users continue to grow after the transition, whether transactions translate into durable revenue, and whether the restored credit service can rebuild without another disruption. The company’s own stated priority is to rebuild fintech momentum.
Competition raises the stakes. Nigerian customers already have several ways to move money, pay merchants and access short-term credit. MTN brings a large telecoms distribution network to that contest, but a network footprint alone does not guarantee daily wallet use. The quality of the payment experience and the economics of each product will matter more than registrations.
TechBooky recently examined Airtel Africa’s data-led growth. MTN’s latest disclosure illustrates the other side of the telecoms-fintech ambition. Digital finance may become an important growth engine, but its components can move in opposite directions. For now, the accurate reading is that MoMo’s core business accelerated sharply while MTN Nigeria’s overall fintech revenue remained below last year’s level.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Femi Balo is the founder and publisher of TechBooky. He covers artificial intelligence, African technology, digital infrastructure, enterprise technology and the global digital economy.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.