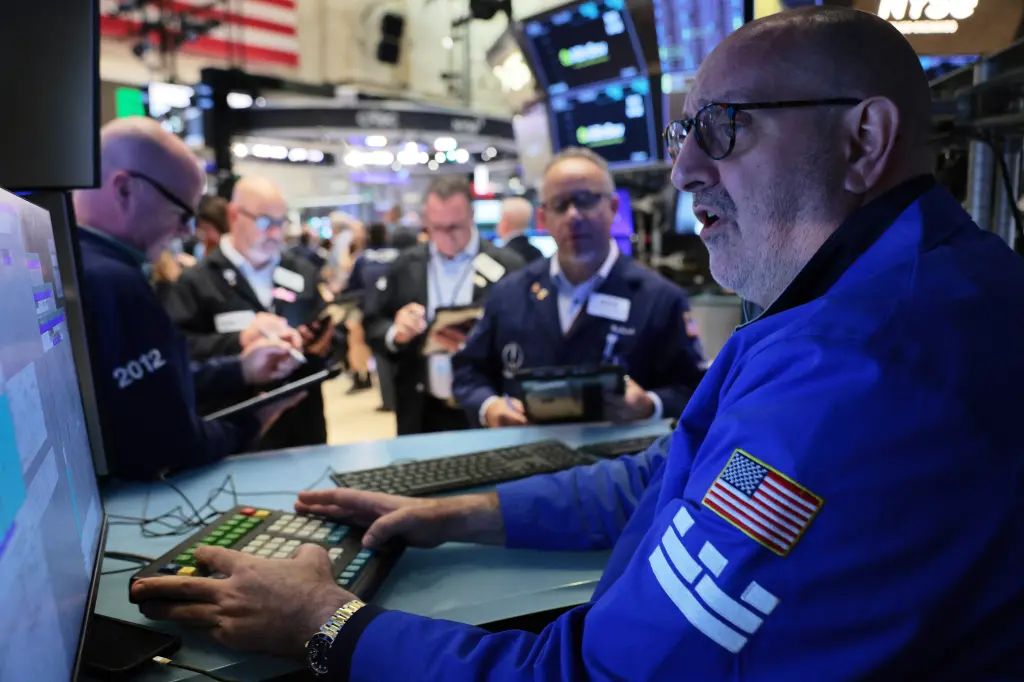
A sharp fall in technology shares across the US and Asia has put a familiar question back in front of investors. The world’s largest technology companies are selling more AI-related services, but are they spending too much, too quickly, to build the infrastructure behind them?
The immediate answer from markets has been uncomfortable. Alphabet shares fell 12.6% in Thursday’s US session, according to Reuters’ market report. On Friday, technology shares weakened in Asia and US futures pointed lower after Amazon and Intel published their results. The moves are a reaction to several different company stories, not evidence that demand for AI has disappeared.
The awkward part of this sell-off is that AI and cloud revenue are still growing. Amazon said its AWS cloud business grew 39% year on year in the third quarter. Yet the company also expects to spend about $220 billion on capital expenditure in 2026, according to its earnings announcement. That is an enormous commitment to data centres, chips and the systems needed to run them.
Our earlier report on Amazon’s earnings covered the individual numbers. The broader market issue is the gap between a growing AI business and the cash required to keep expanding it. A company can report higher sales and operating profit while its spending on new facilities eats into free cash flow. Those are not contradictory outcomes, but they can make a fast-growing company harder to value.
Alphabet presents a similar tension. Its cloud business reported rapid growth, but the scale of spending weighed on cash generation. As TechBooky’s analysis of Alphabet’s quarter noted, the question is no longer whether AI can attract customers. It is how long the company must invest before those customers produce returns large enough to justify the cost.
Not every falling share tells the same story
It would be tempting to label every decline an AI backlash. Intel’s troubles, however, also involve its own manufacturing costs, cash requirements and the performance of its PC business. Its data centre revenue rose sharply, as we reported in our Intel earnings coverage, but that does not erase the challenges elsewhere in the company. Investors are weighing different risks under one broad AI-spending headline.
The timing amplified those worries. After Alphabet’s Thursday decline, Amazon and Intel came under pressure in extended trading. AP reported on Friday that their results were weighing on US futures. Such after-hours and premarket moves can change before regular trading begins, so they are better read as a snapshot of sentiment than a final verdict on either company.
The investment test ahead
The next phase of the AI boom may be judged less by headline revenue growth than by the economics behind it. Investors will look at how much capacity is actually being used, whether cloud margins hold up, and when cash flow improves after construction bills are paid. They will also watch whether demand comes from paying customers with durable workloads or from a smaller circle of companies financing one another’s expansion.
There is also a time-lag problem. A data centre can take years to plan and build, while AI chips may become outdated much sooner. If customers keep buying enough compute at attractive prices, today’s heavy spending could prove sensible. If prices fall or demand grows more slowly than expected, companies could be left carrying costly assets. The market is trying to price that uncertainty before the answer is known.
For readers outside Wall Street, the sell-off matters because it could shape how aggressively the biggest platforms build cloud capacity and what they charge businesses for AI services. It may also influence suppliers across the global chip, power and data-centre chain. A weak trading day does not mean the AI rush is over. It does mean investors are asking for clearer proof that the next dollar spent on AI infrastructure will earn more than it costs.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Femi Balo is the founder and publisher of TechBooky. He covers artificial intelligence, African technology, digital infrastructure, enterprise technology and the global digital economy.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.