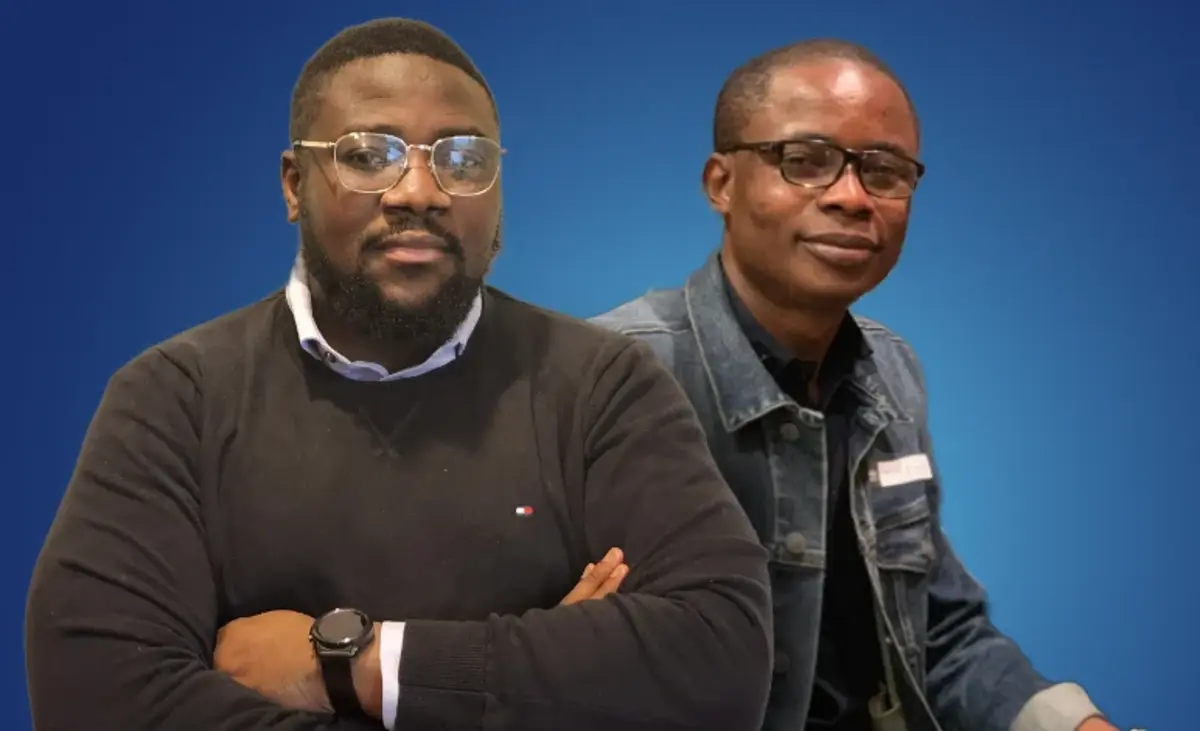
Klump, the Nigerian buy-now-pay-later startup that offered instalment payments at checkout for merchants including Jumia and Konga, is shutting down after five years. Co-founders Celestine Omin and Olufunbi Falayi confirmed the decision in a farewell note published on 25 October. They said the company had raised approximately $1.2 million across a seed round and an extension but could not secure the debt funding needed to expand its own lending operation.
The news lands only months after TechBooky covered Klump’s integration with Jumia. At the time, placing financing inside a major online marketplace looked like a route to more shoppers. The founders’ account shows why distribution alone was not enough: the startup struggled to control both the money behind each loan and the pace at which outside lenders connected to its platform.
Klump began with a straightforward promise. A shopper would select an instalment option at checkout and receive a lending decision quickly enough to complete the purchase. To make that possible, the company initially kept loans on its own book. It could underwrite customers directly, set its risk appetite and finance purchases that established lenders might avoid. But a growing loan book needs capital separate from the money that pays engineers, operations staff and other business costs. The founders said their attempt to raise the required debt did not produce enough funding.
Klump then became a marketplace connecting shoppers and merchants with commercial banks, microfinance banks and finance houses. Under that model, a customer choosing Pay with Klump could select a lender and receive a decision through the checkout system. The lender supplied the financing and carried the credit risk; Klump provided the technology. This reduced Klump’s need to finance every purchase itself, but made its service dependent on partner institutions’ systems and decisions.
The founders said a lending partnership could take six to 18 months from early discussions through integration, testing and launch. Some commercial and legal processes stretched to nearly three years. Banks also controlled which sectors and loan sizes they would support. Meanwhile, Klump had to cover its own operating expenses while it waited. The company said many lenders’ underwriting systems were not built for an outside checkout platform, forcing the team to help design integrations and then work through compliance reviews.
Klump explored a sale as another route forward. The founders said acquisition interest in late 2023 ended after months of due diligence because the parties were not aligned. At the beginning of 2026, they chose to seek a buyer rather than raise more capital, believing buy-now-pay-later would work better as an added service inside a larger financial business than as a standalone company. They spoke with several fintech firms and received an offer, but ultimately declined it. They did not identify the bidder or disclose the proposed price or their precise reason for refusing.
The company said it had supported hundreds of merchants and thousands of customers during its run. It also built Klump Commerce for merchants without their own online shops. Those figures and its claim that merchants reduced cart abandonment by as much as 45% come from the founders’ account; they do not establish that the model could generate enough revenue to sustain the company.
Klump’s experience exposes a difficult trade-off in consumer finance. Lending from a startup’s own balance sheet can preserve speed and control, but scaling it demands reliable funding and disciplined management of defaults. Acting as a software layer for banks reduces that balance-sheet burden, yet delays, cautious underwriting and commercial negotiations can slow the product just when merchants need an instant checkout decision. Neither approach removes the need to earn enough from transactions to cover integration and operating costs.
The shutdown should not be read as proof that Nigerian shoppers have no appetite for instalment payments. It is evidence that demand and merchant reach do not, by themselves, solve the financing problem. Klump’s founders still see access to credit as an unmet need, but their conclusion is that the service may fit more naturally within a larger platform that already has capital, customers and lending infrastructure.
The founders’ note did not set out a timetable for closing customer accounts, handling outstanding repayments or transitioning merchants. Anyone with an active Klump-financed purchase should check their agreement and official communications from the lender involved rather than assume the company’s closure cancels a repayment obligation. For merchants, the immediate question is which financing option now appears at checkout and how existing transactions will be serviced.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Femi Balo is the founder and publisher of TechBooky. He covers artificial intelligence, African technology, digital infrastructure, enterprise technology and the global digital economy.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.