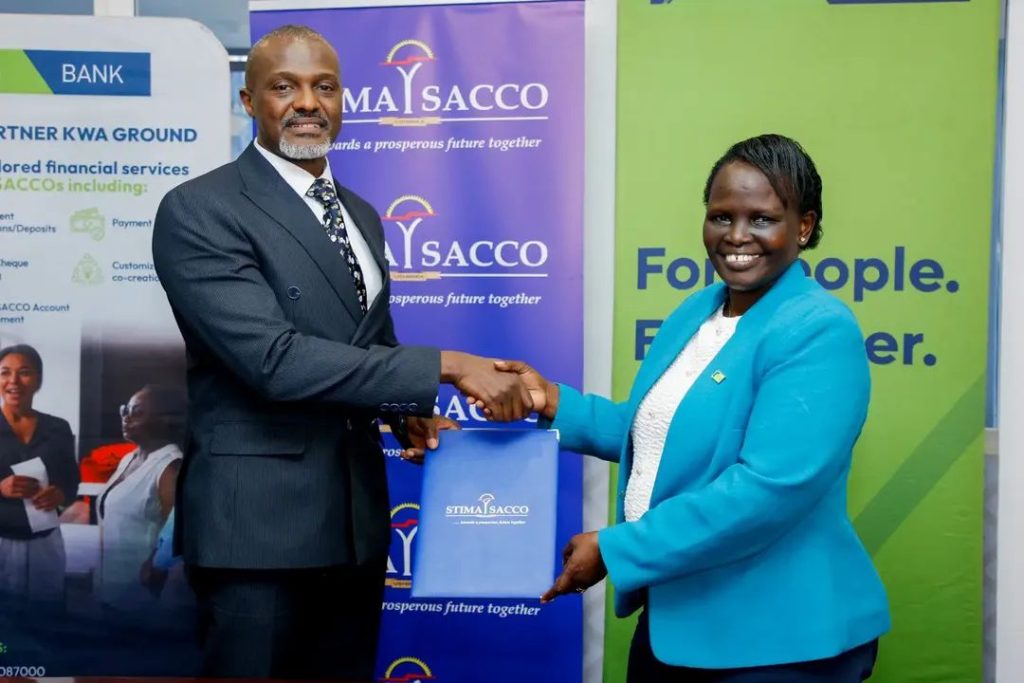
KCB Kenya and Stima Sacco have joined up to make it easier for members to put money into their cooperative accounts. Under the partnership announced in Nairobi, Stima members can make deposits directly through the revamped KCB Mobile Banking App. It is a practical change, especially for people who already use the bank’s app and would otherwise have to move between channels to fund their Sacco account.
The arrangement connects two parts of Kenya’s financial system that many customers use side by side. A bank account handles everyday payments and transfers, while a Sacco can be the home for regular savings and access to cooperative credit. Making the deposit path simpler does not transform either institution overnight, but it removes one small obstacle from a recurring task. For members who contribute often, that convenience can matter more than a flashy new feature.
The announcement is about deposits into Stima Sacco accounts. It does not, on the information released so far, establish that members can withdraw Sacco savings through the same flow, apply for loans in the KCB app or use the service without fees. Those details will matter to customers comparing the new route with their existing ways of making contributions. The partners should also make it clear how quickly deposits appear, what confirmation a member receives and whom to contact if a transaction does not reconcile.
KCB already describes Sacco banking services that support payments toward savings, shares and loan repayments across its channels. The Stima connection makes that wider push more tangible for a specific group of members. It also underlines why interoperability is such a useful goal in Kenyan finance. People do not organize their money around one provider, and a smoother path between institutions can save time without requiring customers to abandon the relationships they trust. A similar push to connect familiar financial channels is visible in Airtel Money and Absa Bank Kenya’s work on SME payments.
That is particularly relevant to Saccos, which play a substantial role in how Kenyans save and borrow. Digital access can help a cooperative serve members who do not live or work close to a branch, but the experience has to be reliable. A convenient deposit button loses its appeal if a customer cannot see whether the money arrived or has to chase support across two institutions.
For now, the significance of the KCB-Stima agreement is straightforward. It gives Stima members another digital route to deposit funds and gives KCB a closer role in routine cooperative banking. The test will be whether the process feels seamless in everyday use, with clear charges, prompt confirmation and dependable support if something goes wrong.
Related Reading
More contextual TechBooky stories selected from tags, categories and article context.
Paul Balo is the founder of TechBooky and a highly skilled wireless communications professional with a strong background in cloud computing, offering extensive experience in designing, implementing, and managing wireless communication systems.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.